
UAE trading company setup in India begins with a single query: Will you export to India from Dubai, or will you require an Indian company that imports, stocks, and bills the goods in India?
India’s FDI Policy allows 100% foreign ownership in wholesale and export trading through the automatic route, so trading is one of the simpler entry points for a UAE business.
This guide covers FDI rules, the import-export code (IEC), GST on imports, customs duty, bonded warehouse options, and ongoing filings under FEMA 1999, the Companies Act 2013, the Customs Act 1962, and the GST Acts 2017. For the general incorporation walkthrough, see our guide to setting up a company in India from the UAE.
Quick Answer: What a UAE Trading Company Needs in India
Five items cover most UAE trading company setups.
- Entity: UAE traders who import goods and bill Indian customers directly generally do so through a private limited company incorporated in India.
- FDI: Wholesale, export trading and B2B e-commerce allow 100% ownership under the automatic route.
- Registrations: You will need a PAN and TAN for the company, a GST number, an IEC from DGFT, and a login on the ICEGATE customs portal.
- Duty: BCD, a Social Welfare Surcharge of 10% of BCD, and IGST, which registered traders can generally claim as credit.
- Filings: FC-GPR within 30 days of share allotment, FLA return by July 15, IEC update every April to June.
Why UAE Trading Company Setup in India Is Gaining Momentum in 2026?
Trade crossed $100 billion under the India-UAE CEPA and edged higher in FY 2025-26.
Indicator | FY 2025-26 | Source |
Bilateral merchandise trade | $101.25 billion (prior year $100.03 billion) | Indian Embassy, UAE |
India’s imports from UAE | $63.89 billion | Indian Embassy, UAE |
India’s exports to UAE | $37.36 billion | Indian Embassy, UAE |
Cumulative UAE FDI, Apr 2000 to Mar 2026 | $25.59 billion | |
CEPA Certificates of Origin since May 2022 | 4.45 lakh | PIB release 2290437, 28 July 2026 |
Joint trade target | $200 billion by 2032 | PIB release 2290437, 28 July 2026 |
What the numbers suggest (MSNA analysis)
- About 63% of corridor trade is India importing from the UAE, so demand for UAE-sourced goods is the larger side.
- UAE FDI for April to December 2025-26 was $2.45 billion against $4.34 billion for all of 2024-25. The periods differ, but trade-led entry may be outpacing capex-led entry. This is our interpretation.
- Rising bilateral volumes are a main reason more UAE businesses now plan to trade in India through a local entity instead of relying only on exports.
What Does UAE Trading Company Setup in India Involve?
Your UAE trade license covers UAE activity only, so India regulates each trading model separately.
Model | Sell in India? | Tax position | Fits when |
Export to an Indian importer | No; buyer is importer of record | UAE entity; check permanent establishment | Testing demand |
Yes | 22% concessional rate for domestic companies, plus surcharge and cess | Regular imports, local invoicing | |
Only RBI-permitted activities | 35% base rate plus surcharge and cess | Parent wants direct presence | |
Liaison office | No; cannot earn income | Generally none | Buyer liaison only |
Note: The Income-tax Act, 2025 applies from 1 April 2026, so Tax Year 2026-27 is the first year under it. The 22% option for domestic companies appears as Sec. 115BAA of the Income-tax Act, 1961 and is placed at section 200 of the 2025 Act.
Is “Trading Company” a Legal Entity Type Under Indian Law?
No. Trading is not an organizational form in India; it is rather a business function.
One private limited company can carry out trading, services or manufacturing; what it may actually do is set by the objects in its charter documents and by the FDI rules for that sector. A ‘trading company’ is simply a company whose main activity is buying and selling goods.
- Company type (private limited, LLP or branch) decides liability, tax rate and ownership rules.
- Trading activity decides the FDI route, IEC, GST and customs requirements.
- Objects clause: State your trading activities clearly in the Memorandum of Association at incorporation.
Our guide to types of companies in India compares the entity options in full.
FDI Rules for UAE Trading Company Setup in India
The FDI Policy decides which trading activities a foreign-owned company can run.
Activity | FDI cap and route | Key condition |
Wholesale and export trading | 100%, automatic | Business buyers only |
B2B e-commerce | 100%, automatic | No retail |
Inventory-based e-commerce | Generally not permitted | Inventory-based export of goods manufactured or produced in India; policy statement dated 23 July 2026, pending formal notification. Domestic B2C inventory remains prohibited. |
Single-brand retail | 100%, automatic | 30% local sourcing above 51% FDI |
Multi-brand retail | 51%, government | $100 million minimum |
These conditions decide which products and buyers your UAE trading company set up in India can serve. A UAE trader who re-exports imported goods is not covered by this relaxation. Treat the restriction as continuing until the formal notification is issued.
Wholesale conditions UAE traders often miss
To be treated as wholesale, you must sell to the right kind of buyer and keep sales to related group entities within the permitted share.
- Buyers must hold a valid business registration or trade license.
- Sales to group companies cannot exceed 25% of turnover, which matters if a UAE parent supplies its Indian affiliates.
- No retail shops, and daily records of buyer and sale details.
- Wholesale includes bulk imports with sales from ex-bonded warehouses.
Who counts as a valid business buyer?
The policy accepts buyers with sales tax, VAT or excise registration, a trade license, a retail permit, or institutions registered for their own consumption. Any one is enough. Paragraph numbering differs across FDI Policy editions, so confirm against the current DPIIT text.
Import Business Setup India: Step-by-Step Roadmap
Following this order helps reduce common rework.
Step | Action | Authority | Output |
1 | Classify goods by HS code; check import policy | DGFT, CBIC | Duty rate, license need |
2 | Incorporate and open a current account | MCA, AD bank | CIN, PAN, TAN |
3 | Bring in capital and report it | RBI via AD bank | FC-GPR in 30 days |
4 | Apply for IEC | IEC | |
5 | Register for GST | GST portal | GSTIN |
6 | Register on ICEGATE; appoint a customs broker | CBIC | Bill of Entry access |
7 | Obtain product approvals | FSSAI, CDSCO, BIS | Clearance-ready goods |
Starting with HS classification and ending with product approvals keeps the first shipment from stalling at the port. If you prefer professional support, MSNA’s company registration services for UAE businesses in India can assist with incorporation, GST and IEC.
If you also export from India, register your bank’s AD code with customs at the port of shipment and file a Letter of Undertaking (LUT) on the GST portal each financial year, so you can export without paying IGST. Missing either is one of the usual first-shipment gaps, and it can block a refund or hold a shipping bill.
Import Export Code (IEC) Registration in UAE Trading Company Setup in India
The IEC is mandatory for importing, so it anchors any import business setup India plan. Without an IEC, your UAE trading company setup in India cannot clear its first import shipment.
Item | Detail |
Issued by | DGFT, to the Indian entity (not the overseas parent) |
Linked to | PAN; one IEC per PAN |
Fee | ₹500, one-time |
Validity | Lifetime, with a mandatory update each April to June |
A missed update deactivates the code, so calendar it. Our IEC registration guide covers the portal steps.
GST on Imports: What a UAE Trading Company Pays and Recovers
Customs collects IGST at the port, and a registered importer can generally claim it as input credit.
Since September 22, 2025, GST runs on 5%, 18% and 40% slabs (Tribune), so guides quoting 28% are outdated. Our GST registration for foreign-owned companies guide lists the documents.
Why a GSTIN matters on the first shipment
IGST is paid at the port either way, but without a GSTIN you cannot claim it back as credit.
2026 GST process updates
The 57th GST Council (October 8, 2026) kept rates unchanged and recommended process reforms that still need notification.
Area | Recommendation |
Registration | Low-risk applications approved in 3 working days |
Refund acknowledgment | Cut from 15 to 10 days |
Zero-rated refunds | About 90% provisionally sanctioned automatically |
Customs Duty for UAE Trading Company Setup in India
Customs duty is where margin surprises usually appear, and three layers stack up.
- BCD: Set per HS code under the Customs Tariff Act, 1975.
- SWS: Generally 10% of BCD.
- IGST: 5%, 18% or 40% on value plus BCD plus SWS.
Worked example: landed cost on a ₹10 lakh CIF shipment
Illustrative example, not a client case. This example assumes BCD 10%, SWS 10% of BCD and IGST 18%; your HS code sets the real rates.
Component | Amount (₹) |
BCD (10% of 10,00,000) | 1,00,000 |
SWS (10% of BCD) | 10,000 |
IGST (18% of 11,10,000) | 1,99,800 |
Total paid at port | 3,09,800 (about 31%) |
Net cost after IGST credit | 1,10,000 (about 11%) |
Our reading: the cash outlay is about 31%, but the lasting cost is closer to 11%. The gap is working capital until the credit is used.
Budget 2026 customs changes that matter to traders
Three 2026 changes affect commercial importers, while one headline change does not.
- Deferred duty payment for trusted entities (AEO Tier 2/3 and eligible manufacturer importers) extended from 15 to 30 days from 1 March 2026 (Notification 13/2026-Customs (NT)). New importers typically pay at import. A newly set-up trading company will not qualify at the start, so budget working capital for payment at the port.
- Certain concessional BCD rates moved into the First Schedule from May 1, 2026, so re-check rates on ICEGATE.
- The personal-use duty cut from 20% to 10% (heading 9804) does not apply to stock bought for resale.
How CEPA preference works for UAE-origin goods?
Preferential rates depend on proof of origin, not on shipping from the UAE.
- A Certificate of Origin from a UAE government agency is needed at clearance.
- Most industrial goods need a tariff-heading change plus 40% value addition (EY).
- Gold is covered by a CEPA tariff rate quota (200 tonnes announced in 2022) at a concessional duty rate.
Bonded Warehouse Options for Trading Operations
A bonded warehouse defers customs duty until goods leave for home consumption; it does not waive it. For high-duty or slow-moving stock, a bonded warehouse can ease cash flow for a new importer.
Option | Duty paid | Best for |
Pay at import | Before clearance | Fast-moving stock |
Deferred payment (trusted entities) | Within up to 30 days | AEO Tier 2/3 and eligible manufacturer importers |
Bonded warehouse | At home-consumption clearance | Slow-moving or re-export stock |
- Warehouses are licensed under Sections 57, 58 and 58A of the Customs Act, 1962.
- Duty is charged at the rate on the date the home-consumption Bill of Entry is filed.
- On the ₹10 lakh example, ₹3,09,800 of duty would be deferred.
- Section 65 (MOOWR) permission covers manufacturing in bond, so most pure traders do not need it.
Trading License India: Registrations Beyond the IEC
India has no single trading license, so you assemble a set of registrations.
Registration | Authority | Applies when |
Incorporation, PAN, TAN | MCA, Income Tax Dept | Every company |
GSTIN | GST portal | Selling goods, claiming credit |
Shops and Establishment or trade license | State or municipal body | Office or warehouse premises |
FSSAI, CDSCO, BIS, Legal Metrology | Respective bodies | Food, drugs, notified or packaged goods |
RCMC | Export promotion council | Export benefits |
Tax and FEMA Compliance for an India Entity for UAE Traders
Once trading starts, the India entity for UAE traders carries recurring filings in both countries.
Obligation | Timing |
FC-GPR | Within 30 days of share allotment |
GSTR-1 and GSTR-3B | Monthly or quarterly |
MCA filings and statutory audit | Annually |
Form 3CEB (related-party deals) | Annually |
FLA return | By July 15 |
IEC update | April to June |
See our notes on annual compliance and statutory audit. At least one director must be an Indian resident for 182 days or more.
India vs. UAE tax snapshot
Both countries tax the same profits, so treaty relief matters.
- India: 22% concessional rate for a domestic company (Sec. 115BAA of the 1961 Act; section 200 of the 2025 Act; 35% base for a foreign company.
- UAE: 9% corporate tax above AED 375,000; 5% VAT.
- The India-UAE DTAA caps withholding at 10% on dividends and royalties and 5% to 12.5% on interest.
Related-party pricing
A Dubai parent selling to its Indian subsidiary creates a transaction that tax officers review.
- Price at arm’s length and keep benchmarking files.
- File Form 3CEB where thresholds apply; see our transfer pricing guide.
Which Route Fits Your Trading Profile?
Match your volumes and stock profile to the entry model.
Your situation | Likely fit |
Two or three shipments to known buyers | Export to an Indian importer |
Regular imports sold to wholesalers | Private limited company |
Slow-moving, high-duty stock | Private limited company plus bonded warehouse |
Online sales to Indian consumers | Rethink; inventory-based B2C is generally not permitted |
A qualified professional can help you assess which entry model fits your product and volume.
Common Mistakes in UAE Trading Company Setup in India
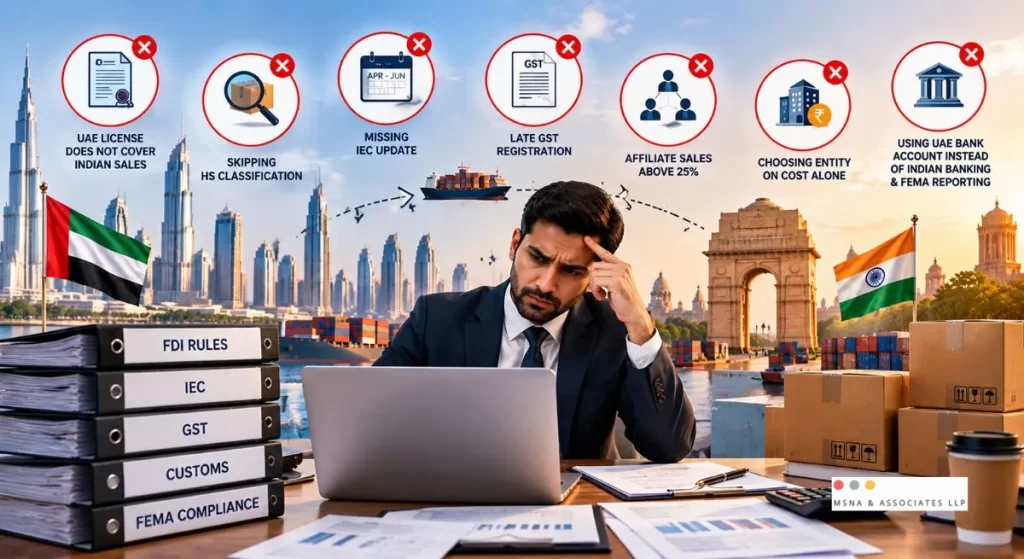
These errors recur in cross-border trading setups.
- Assuming a UAE license covers Indian sales.
- Skipping HS classification.
- Missing the April to June IEC update.
- Late GST registration and forfeiture of initial IGST benefit.
- Sales made to affiliates above 25%.
- Choosing an entity on cost alone, without checking FDI conditions.
- Treating a UAE bank account as a substitute for Indian banking and FEMA reporting
When UAE Trading Company Setup in India May Not Fit ?
A full Indian entity is not always the right answer for a trading business.
- You plan retail shops or direct sales to consumers.
- Your goods are restricted and need case-by-case import authorization.
- You ship only occasionally, so an Indian importer of record may be enough.
Next Step For UAE Trading Company Setup in India
Speak with a chartered accountant before finalizing your UAE trading company setup in India, so entry model and duty treatment match your product and volume.
In case you are setting up an India trading company for the UAE, you may approach the team at MSNA or check out our India company registration for UAE firms
Planning to Set Up a UAE Trading Company in India?
Frequently Asked Questions About UAE Trading Company Setup in India
Can a UAE company trade in India without an Indian company?
Yes, by exporting to an Indian importer who handles customs. Direct sales to Indian customers need an Indian entity.
Is 100% FDI allowed in a trading company?
For wholesale, export trading and B2B e-commerce, yes, under the automatic route and subject to conditions.
Do I need GST registration to import?
IGST is collected at the port regardless. Registration lets you claim it as credit and invoice locally.
How much does an import export code cost?
The DGFT fee is ₹500, one-time, with no fee for the annual update if done in April to June.
Can I import duty-free through a bonded warehouse?
No. Duty is deferred, and interest can apply if goods stay beyond the permitted period.
Related
Discover more from MSNA & Associates LLP
Subscribe to get the latest posts sent to your email.