
A signed term sheet is a commitment to investigate, not a commitment to invest. The gap between the two is startup due diligence: the structured verification of a company’s finances, legal standing, team, cap table, intellectual property and market before capital is released. This startup due diligence checklist sets out what Indian investors review under the Companies Act, 2013, FEMA and the Income-tax Act. Founders can use it to prepare their records. Investors can use it to structure their enquiries.
Key Takeaways
- A standard diligence review is usually completed within two to six weeks. Well-maintained records shorten the period.
- Five areas determine most outcomes: financials, legal compliance, cap table, intellectual property and team.
- Section 56(2)(viib) does not apply from AY 2025-26 (Finance (No. 2) Act, 2024). Angel tax is therefore no longer a pricing risk for new rounds, but source-of-funds verification continues.
- An organised data room is an early signal of investor readiness, because it shows the records already exist.
What Is Startup Due Diligence?
Startup due diligence is verification, not assumption. Investors compare the claims in a pitch deck with documentary evidence. A common classification, used by InnMind, divides the review into team, market, product and financial diligence.
Type | Scope of review | Usually led by |
Financial | Books, tax position, burn, runway | Chartered Accountant / CFO |
Legal | Incorporation, contracts, shareholder agreements | Lawyer / Company Secretary |
Commercial | Market analysis, customers, revenue model | Investor deal team |
Technical | Product, code, security | Technical expert |
Team | Founder background verification | Investor deal team |
Why It Matters to Founders and Investors
- Founders: fewer surprises, a shorter closing timeline and less room for the valuation to be revised
- Investors: risks are priced before capital is committed.
- Deal risk: Ansarada reports that 47% of deals fail because of issues identified during diligence. This is a vendor-reported figure and should be read as indicative.
Startup Due Diligence in India: 2026 Data Snapshot
Indicator | Latest figure | Source |
Tech startup funding, 2025 | $10.5 billion, down 17% from $12.7 billion | |
Global rank | Third, after the US and UK | Tracxn |
Rounds of $100 million or more | 14 (19 in 2024) | Tracxn |
Seed funding | $1.1 billion, down 30% | Tracxn |
Early-stage funding | $3.9 billion, up 7% | |
Tech IPOs | 42 (36 in 2024) | Tracxn |
Share of funding | Bengaluru 32%, Mumbai 18% | Tracxn |
DPIIT-recognised startups | Over 2.23 lakh at 31 March 2026; over 55,200 added in FY26 |
Our assessment of these figures:
- Capital is more selective, so investors examine companies more closely before committing.
- Seed funding declined while later early-stage rounds grew. Seed-stage founders now compete for fewer cheques.
- Annual DPIIT recognitions rose 51.6% in FY26 (from over 36,400 in FY25). More recognised startups competing for the same capital makes clean records a differentiator.
Startup Due Diligence in 2026: Regulatory Changes Investors Now Review
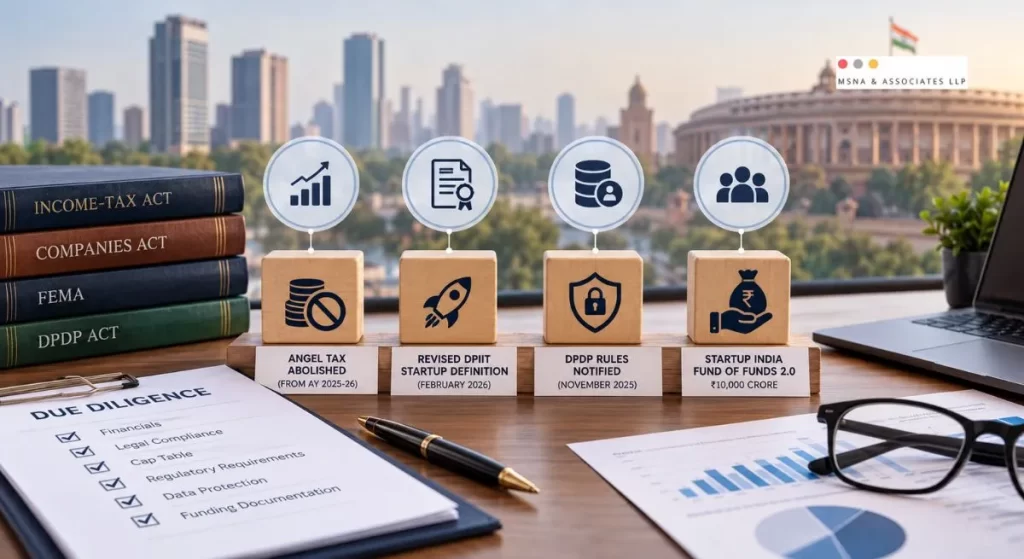
Four recent developments shape how startup due diligence is conducted in India.
Change | Effect | Relevance to diligence |
Angel tax abolished (from AY 2025-26) | Section 56(2)(viib) does not apply from AY 2025-26 (Finance (No. 2) Act, 2024). The Income-tax Act, 2025 (effective 1 April 2026) does not carry it forward (Incorpx) | Retain valuation papers for shares issued before FY 2024-25, as earlier rounds may still draw questions. Rounds from FY 2024-25 onward carry no angel tax exposure. |
Revised DPIIT startup definition (February 2026) | Turnover ceiling raised from ₹100 crore to ₹200 crore, with a new deep tech category (20 years, ₹300 crore) (Nishith Desai Associates) | Recognition status and supporting documents are verified, not assumed |
DPDP Rules notified (November 2025) | Consent Manager registration (Rule 4) takes effect on 13 November 2026, and most other duties take effect on 13 May 2027 (King Stubb & Kasiva). | Investors ask whether a data inventory and consent records exist. Most startups are not Consent Managers, so the main exposure begins in May 2027, but investors are already asking. |
Startup India Fund of Funds 2.0 | Corpus of ₹10,000 crore notified (Inc42) | In our assessment, fund-backed rounds tend to follow formal diligence templates |
Our assessment: regulations are changing faster than founder paperwork. Diligence teams increasingly require dated proof of status, not only a certificate.
Startup Due Diligence Process: Six Stages
The startup due diligence process follows a defined sequence. VCBeast places the typical duration at two to six weeks from term sheet to closing.
Stage | Activity | Typical timing |
1. Term sheet and NDA | Exclusivity and scope are agreed | Day 0 |
2. Data room opens | Founder uploads documents | Week 1 |
3. Document review | Financial and legal teams review records | Weeks 1 to 3 |
4. Management Q&A | Calls with founders and key customers | Weeks 2 to 4 |
5. Findings and negotiation | Issues translate into price or conditions | Weeks 3 to 5 |
6. Final agreements | Shareholder and subscription agreements are executed | Weeks 4 to 6 |
Timings are indicative and vary with deal size.
Outcomes of Startup Investment Due Diligence
Startup investment due diligence concludes with a findings report. Its contents determine the next step.
Finding | Likely outcome |
Clean records, minor queries | Final agreements proceed |
Remediable gaps (filings, IP assignments) | Conditions precedent to closing |
Valuation or revenue differences | Renegotiated price or tranche-based funding |
Serious unresolved issues | Investor may pause or withdraw |
Founders should therefore remedy known gaps before the data room opens. Startup investment due diligence proceeds more smoothly when every answer already exists in writing.
Startup Due Diligence Checklist: Seven Areas of Review
1. Founder Background Verification and Team
- Identity, PAN, address and DIN details
- Education and prior roles, matched to the pitch
- Other directorships on the MCA portal
- Litigation, credit and reference checks
- Founder vesting and time commitment
- Employment agreements containing IP assignment clauses
2. Financial Due Diligence for Startups
Financial due diligence for startups tests whether reported figures are accurate, repeatable and reconcilable.
Area | Documents to prepare | Investor enquiry |
Financial statements review | Two to three years of accounts, monthly MIS | Do the figures reconcile to bank statements? |
Revenue model validation | MRR/ARR, cohorts, customer concentration | Is revenue recurring or one-off? |
Burn and runway | Monthly burn, 18-month forecast | How many months of cash remain? |
Tax filings | Income-tax returns, TDS, GSTR-1 against GSTR-3B reconciliation (reviewed by our GST advisory team) | Are any notices open? |
Liabilities | Loans, related-party dues | Are there undisclosed obligations? |
Professional note: a pre- diligence financial readiness assessment by a Chartered Accountant before investors arrive identifies mismatches early. It should be paired with revenue model validation, showing how each customer segment pays, renews and churns.
Under Section 68 of the Income-tax Act, 1961, unexplained credits can be examined for periods up to FY 2025-26. For FY 2026-27 onwards, the corresponding provision under the Income-tax Act, 2025 applies. Under either Act, retain proof of the source of every investor rupee, and obtain a tax opinion where the treatment is unclear.
3. Legal Due Diligence for Startups
Legal due diligence for startups confirms that the company exists, owns what it claims and is authorised to issue shares.
Area | Documents investors expect |
Incorporation | Certificate, MOA, AOA |
Annual filings | AOC-4, MGT-7, board and AGM minutes |
Share issues | PAS-3 returns, valid resolutions, share certificates |
Shareholder agreements | SHA, prior investor rights, side letters |
Disclosure letter and warranties | Disclosure letter against the representations and warranties in the SHA, with known exceptions listed. Founders carry exposure for any warranty that is untrue at closing, so known issues should be disclosed in writing before signing. |
Foreign investment | FEMA reporting such as FC-GPR (within 30 days of allotment), and the FLA annual return (due by 15 July each year). The annual return is a recurring filing that is easy to miss after FC-GPR, so investors ask for the last filed acknowledgement. |
Foreign investor screening | Press Note 3 (2020) approval where the investor is from, or has beneficial ownership in, a country sharing a land border with India. Approval is needed before allotment, so this check affects the closing timeline. |
Regulatory compliance | Licences, PF/ESI, GST, data privacy under the DPDP Act, 2023 |
Litigation | Notices, disputes, tax proceedings |
4. Cap Table Analysis and Startup Valuation
The cap table is among the schedules investors examine most closely. Cap table analysis confirms that every share, option and convertible instrument is documented.
- Reconcile the cap table to the statutory registers
- Review the ESOP pool, grants and vesting under Section 62(1)(b)
- Check liquidation preference and anti-dilution terms
- Confirm the valuation method and the pre-money and post-money split, with M&A and direct tax implications in view
- For non-resident investors, confirm that pricing meets FEMA fair-value requirements
5. Intellectual Property Rights
- Trademark filings in the company’s name
- Contractor and employee IP assignments
- Open-source licence audit of the codebase
- Domains, patents and copyrights held by the company, not by a founder personally
Weaknesses in intellectual property rights are common in early teams. They are also straightforward to remedy before diligence begins.
6. Business Operations and Market Analysis
- Ten largest customer contracts and concentration
- Unit economics: CAC, payback period, gross margin
- Bottom-up market analysis rather than a top-down TAM estimate
- Documented SOPs and internal controls, which internal audit services can test before investors do
7. Startup Risk Assessment
A sound startup risk assessment ranks issues by severity and remediability. Gaps in regulatory compliance, such as missed ROC or GST filings, are common and generally remediable.
Risk | Example | Severity | Typical remedy |
Reconciliation gaps | Revenue differs between books and GST | High | Reconcile and document |
Undocumented allotments | Shares issued without PAS-3 | High | Regularise filings |
Contractor-written code | Code written by freelancers | High | Obtain assignments |
Customer concentration | One client above 40% of revenue | Medium | Disclose with a mitigation plan |
Missing minutes | Board decisions not recorded | Medium | Ratify through proper process |
Startup Due Diligence Documents: Recommended Data Room Structure
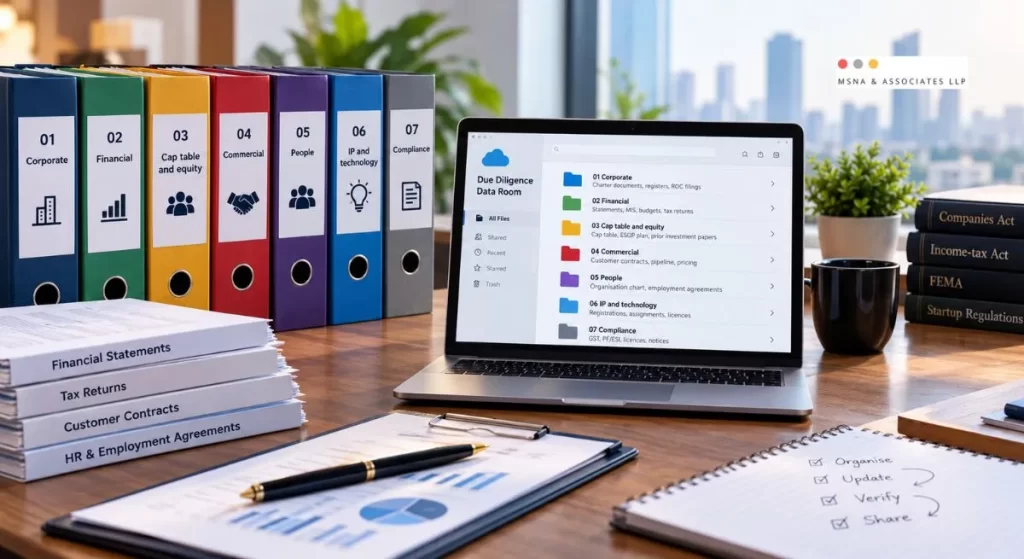
Effective fundraising documentation is organised in the sequence investors review it. Use numbered folders and a single version of each file.
Folder | Contents |
01 Corporate | Charter documents, registers, ROC filings |
02 Financial | Statements, MIS, budgets, tax returns |
03 Cap table and equity | Cap table, ESOP plan, prior investment papers |
04 Commercial | Customer contracts, pipeline, pricing |
05 People | Organisation chart, employment agreements |
06 IP and technology | Registrations, assignments, licences |
07 Compliance | GST, PF/ESI, licences, notices |
These startup due diligence documents also serve as an internal audit trail. They can be reused in later rounds, and foreign-owned startups can pair them with India entity setup and compliance.
Investor Due Diligence Checklist: Weighted Scorecard
This investor due diligence checklist converts findings into a decision. The weights below form an illustrative MSNA framework, not an industry standard, and should be adjusted to the investment thesis.
Area | Weight | Positive signal | Red flag |
Financials | 25% | Books reconcile to bank and GST | Unexplained revenue spikes |
Team | 20% | Verified track record | Unverifiable claims |
Legal and compliance | 20% | Filings are current | Missing allotment forms |
Cap table | 15% | Clean and reconciled | Verbal promises of equity |
Market and revenue | 10% | Repeatable customers | One-off deals only |
IP and technology | 10% | Company owns all IP | Founder-owned code |
Questions Investors Should Ask Founders
Effective questions are specific. The following apply across stages:
- Finance: “What is the monthly burn, and what changed in the last three months?”
- Revenue: “Which customers renewed, and which left? Why?”
- Tax: “Are any notices pending, and how are they being handled?”
- Legal: “Has every share issue been filed and board-approved?”
- Team: “Who owns the code, and who could leave without harming the product?”
- Controls: “Who approves payments, and how are approvals recorded?”
Good answers are concise, documented and consistent with the data room. Hesitation is not a red flag by itself, but a missing document usually is.
Investor Readiness Self-Assessment for Founders
Score one point for each affirmative answer. This is a quick test of investor readiness before any startup investment due diligence begins.
- Are the books closed within 15 days of month-end?
- Do revenue figures match GST returns?
- Are all share allotments filed with the ROC?
- Does the cap table match the statutory registers?
- Are shareholder agreements signed and stored?
- Do all contractors have IP assignment clauses?
- Are board minutes current?
- Are tax filings up to date?
- Is an 18-month forecast available?
- Is a data room ready to share?
8 to 10: well prepared. 5 to 7: address the gaps before launching the round. Below 5: devote a month to foundational records first.
If your score is below 8, a Chartered Accountant can help you assess which gaps matter for your round.
What Mistakes Delay a Funding Round?
- Presenting figures that differ across the deck, the books and GST returns
- Maintaining the cap table in an unshared spreadsheet
- Treating legal due diligence as a task for the closing week
- Overstating market size without bottom-up reasoning
- Concealing known issues instead of disclosing them with a remedy
Illustrative scenario, not a client matter: A seed-stage company reports ₹4 crore of annual revenue in its deck, while its GST returns show ₹3.2 crore for the same year. The difference is traced to advances that were booked as revenue. The investor pauses the review until the gap is reconciled and documented. A gap like this is not fatal, but an unexplained one is treated as a risk until it is explained.
Expert Perspective: Diligence as a Two-Way Assessment
Founders often regard diligence as an examination. It is more usefully regarded as a diagnostic: the same startup due diligence checklist that investors apply also reveals where a company’s own reporting is weak.
Three practices are consistently recommended to growing teams:
- Close the books monthly. Month-end discipline makes every later request easier to answer.
- Maintain one source of truth. The cap table, minutes and contracts should reside in one shared, version-controlled location.
- Request the investor’s list early. Work through it before the formal process begins.
Investors also benefit. Founders who respond promptly and disclose openly are easier to back, which is itself a useful signal.
“Many diligence delays arise from numbers that do not reconcile and approvals that were never documented. A startup that closes its books monthly and keeps its minutes current is better placed to answer diligence requests promptly.”
CA Naveen Nagaraj, Founder Partner, M S N A & Associates LLP
MSNA’s Four-Lens Review
MSNA partners divide a diligence-readiness review by practice area, as listed on the firm’s profile.
Lens | Partner practice area | Typical first checks |
Controls and audit | CA Naveen Nagaraj: internal and statutory audit, SOPs, ICFR | Approval flows, SOPs, control gaps |
Financial reporting | CA Nitesh: Ind AS and assurance | Accounting policies, revenue recognition |
GST | CA Ashwini Magod: compliance, advisory, litigation | GSTR reconciliation, input credit |
Direct tax and M&A tax | CA Madan Hemaraju: representation, appeals, M&A taxation | Return filings, deal structuring |
Conclusion on Startup Due Diligence
Early preparation converts diligence from an obstacle into evidence of governance. Founders should begin with the books, statutory filings, cap table and IP, and then assign a remedy to each gap. Complete fundraising documentation also gives the next round a head start. A pre-diligence readiness discussion with a Chartered Accountant can help map this checklist to your round. MSNA’s virtual CFO services and financial reporting teams work across these areas.
Preparing for Your Next Funding Round?
Frequently Asked Questions About Startup Due Diligence
What is startup due diligence?
This is the investor’s evaluation of a startup’s finance, documents, people, IP and market before investment.
How long does the startup due diligence process take?
Typically two to six weeks, depending on the organisation of the documents.
Which documents are required?
Corporate records, financial statements, tax filings, the cap table, contracts, IP papers and compliance proof. See the data room structure above.
What are the principal red flags for investors?
Unreconciled numbers, undocumented share issues, founder-owned IP and unverifiable claims.
Is angel tax still a concern?
Section 56(2)(viib) does not apply from AY 2025-26 (Finance (No. 2) Act, 2024), which covers shares issued in FY 2024-25 and later. Earlier issues can still draw questions, so retain the valuation papers.
How does diligence differ from an audit?
An audit expresses an opinion on past financial statements. Diligence also tests the legal position, the market and future potential.
Related
Discover more from MSNA & Associates LLP
Subscribe to get the latest posts sent to your email.