
Incorporation is rarely where foreign investors struggle in India. Investing in the Indian company is a one-time action, while looking after its accounts and filings is a continuing responsibility that never really pauses. That means keeping books your head office can consolidate, meeting tax and FEMA deadlines on the Indian calendar, and maintaining a dependable view of cash.
For an overseas parent, a virtual CFO for foreign investor-owned businesses is a part-time finance executive, typically a Chartered Accountant. This is a named lead who prepares and reviews the Indian entity’s accounts, tax and FEMA filings, cash forecasts and HQ reporting, working with the directors, statutory auditor and company secretary, who keep their own statutory responsibilities.
It matters most after India entry, when a foreign investor in India has bank accounts, payroll and filings but nobody local who signs off the numbers. Under the Companies Act, 2013, FEMA, 1999 and the Income-tax Act, 2025 (effective 1 April 2026), each obligation runs on its own Indian clock.
This guide explains how CFO services for foreign companies close that gap, what changed in 2026, and what to check before you hire.
Key Takeaways
- Overseas owners cannot easily question the numbers of an Indian subsidiary if nobody senior is in the country to answer for them. A virtual CFO for foreign investor-owned entities closes that gap with one named lead. That person coordinates the reported results, the regulatory returns and the payment approval process, while directors, the statutory auditor and the company secretary keep their own sign-offs.
- India drew US58.84billioninFDIequityinFY2025-26,yetnetFDIwasonlyUS7.7 billion. Cash flow and repatriation need planning, not just entry.
- Three clocks run together: Indian statutory dates, RBI/FEMA dates and headquarters reporting dates.
- For FY 2025-26, filings still follow the Income-tax Act, 1961 (Form 3CEB, due 31 October 2026). From Tax Year 2026-27, the Income-tax Act, 2025 and Form 48 apply. IT services pricing can be tested against a 15.5% safe harbour from that year, and exports carry a nine-month realisation deadline, counted from shipment for goods and from the invoice date for services. Pricing models and payment terms drawn up under earlier rules deserve a review before the next filing cycle.
- Audit sign-off and secretarial compliance stay with the statutory auditor and the company secretary. The virtual CFO assists each and replaces neither.
What Are the Responsibilities of a Virtual CFO for Foreign Investor Businesses?
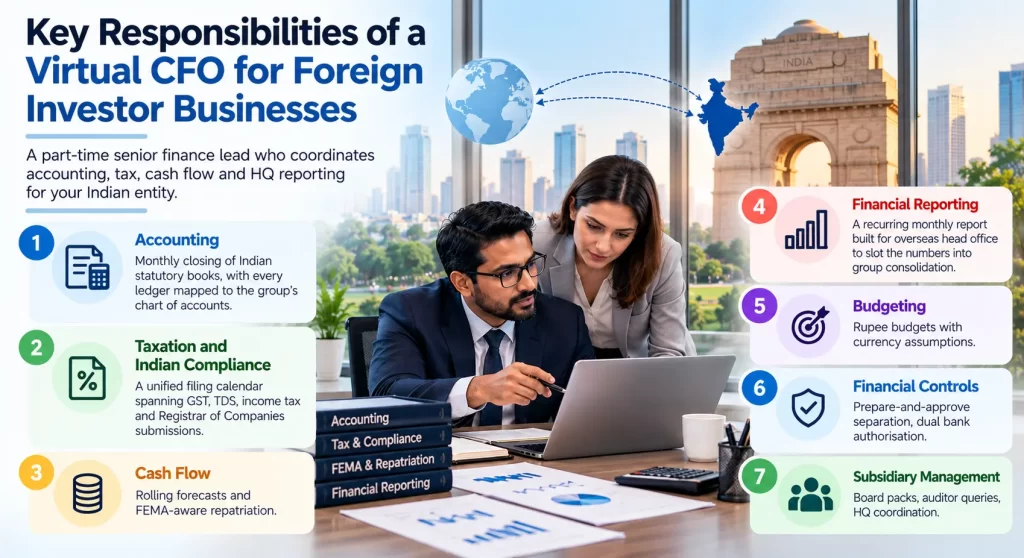
A virtual CFO is a part-time senior finance lead who coordinates accounting, tax, cash flow and HQ reporting for the Indian entity, working alongside the auditor, company secretary and directors.
A virtual CFO for foreign investors covers seven areas:
- Accounting: monthly closing of the Indian statutory books, with every ledger mapped to the group’s chart of accounts
- Taxation and Indian compliance: a unified filing calendar spanning GST, TDS, income tax and Registrar of Companies submissions
- Cash flow: rolling forecasts and FEMA-aware repatriation
- Financial reporting: a recurring monthly report built so overseas head office can slot the numbers into group consolidation
- Budgeting: rupee budgets with currency assumptions
- Financial controls: prepare-and-approve separation, dual bank authorisation
- Subsidiary management: board packs, auditor queries, HQ coordination
MSNA’s virtual CFO services follow this structure. ICAI also lists outsourced CFO services among the professional services Indian CA firms offer foreign entities.
Why Does Finance Become the Biggest Challenge After Entering India?
Capital is arriving faster than finance functions are being built. DPIIT data reported for FY 2025-26 show record inflows.
Indicator | Figure | Source |
FDI equity inflows, FY 2025-26 | US$58.84 bn (+18%) | DPIIT |
Total FDI (equity, reinvested earnings, other) | US$94.5 bn (+17%) | DPIIT |
FDI from the US | S11.17bn(FY2024-25:US5.45 bn) | DPIIT |
Top states | Maharashtra US18.41bn,KarnatakaUS12.93 bn | DPIIT |
Net FDI after repatriation | US$7.7 bn | |
Equity inflow, Q1 FY 2026-27 | US$19.81 bn (+6%); Japan largest | |
FDI from the US, Q1 FY 2026-27 | US1.34bn(Q1FY2025-26:US5.61 bn) | DPIIT |
MSNA analysis:
Net FDI is roughly 8% of gross inflows (US7.7bnagainstUS94.5 bn). Net figures also reflect repatriation and outward investment, so money does leave. The net figure is not a measure of dividend or fee outflows, because it largely reflects equity disinvestment by investors exiting. A foreign investor in India who plans only the inflow leaves the outflow to chance.
Seven Finance Problems After Entering India, and the Virtual CFO’s Approach to Each
A finance lead for an Indian subsidiary does not tackle these as seven separate tasks. A decision in one area changes the position in the others, which is why all seven are handled in one plan.
1. Accounting the Head Office Can Consolidate
Statutory books follow Indian standards. The parent reports under US GAAP or IFRS.
- Every ledger in the Indian books is linked by the virtual CFO to the matching group account code.
- A rolling GAAP adjustment schedule bridges the two views.
- Reconciliations run on a fixed cut-off, as in MSNA’s note on why MIS reports fail.
2. Cash Flow and Repatriation
Profit on paper does not equal cash in the bank. Parent receivables now have a shorter collection window, and any remittance sent overseas has to clear both withholding tax review and the authorised dealer bank’s checks.
- Exporters now have nine months to realise payment. The clock starts at shipment for goods and at the invoice date for services. This applies from 1 October 2026 under RBI regulations. Rupee-denominated invoices are allowed twelve months instead.
- Withholding tax and FEMA treatment differ by payment type, so dividends, service fees, royalties and interest on loans each require separate handling.
- A 13-week forecast and tighter collections, covered in our guide to accounts receivable, protect liquidity.
3. Tax Filing and Withholding Under the Income-tax Act, 2025
The Income-tax Act, 2025 applies from 1 April 2026 and covers tax years from 2026-27, replacing the earlier legislation. The FY 2025-26 return being filed now stays under the Income-tax Act, 1961. A single “tax year” replaces the previous-year and assessment-year pair, per this compliance guide.
- Form 3CEB for FY 2025-26 is due on 31 October 2026 in transfer pricing cases. Form 48 replaces it from Tax Year 2026-27.
- Payments to the parent need a withholding check before the wire leaves.
- Intercompany pricing needs a signed agreement and a cost ledger kept during the year.
Expert insight, CA Madan Hemaraju: “For a foreign-owned subsidiary, transfer pricing is often among the larger tax exposures. Many teams treat it as a year-end filing, yet it works better as a monthly habit: price, document, then invoice”
Pre-Payment Checklist for Parent Invoices
- An executed intercompany agreement, plus proof that the service was actually rendered
- Withholding and GST reverse-charge assessment
- Treaty documents on file where a lower rate is claimed
- Remittance paperwork ready before the wire
4. Financial Reporting to Headquarters
- Begin by choosing the date on which the books will close each month, then plan every reporting deadline in reverse from that date.
- Book accruals for items that have not yet been settled, including GST and TDS liabilities.
- Send a standard pack: mapped trial balance, bank and intercompany reconciliations, accrual schedule, payables ageing, cash forecast and budget variance.
5. Budgeting and Forecasting
Budgets must work in rupees for Indian operations and in HQ currency for group reporting.
- Prepare the budget in rupees and state the currency assumptions explicitly.
- Check cost-plus margins against the positions taken for transfer pricing.
- Assess proposed expenditure using the approach set out in our capex planning guide.
6. Financial Controls
Controls matter most wherever a single individual can both initiate and approve a payment.
- The person who prepares a payment should never be the one who authorises it.
- Enforce dual authorisation on the bank mandate.
- Document SOPs and risk-control matrices, as in our internal audit and ICFR work.
7. Coordination With Overseas Headquarters
Coordination weakens when HQ has several contacts and India has none accountable.
The Three-Clock Model: Why Subsidiary Management Gets Complicated
Most India finance problems are timing problems. Three clocks run at once.
Clock | Set by | Typical items | Who owns it |
Indian statutory | MCA, CBDT, GSTN | GSTR-3B on the 20th; AOC-4 within 30 days of the AGM; MGT-7 within 60 days | Virtual CFO with company secretary |
RBI / FEMA | RBI via the AD bank | Allot shares within 60 days of receipt; FC-GPR within 30 days of allotment; FC-TRS within 60 days; FLA return by 15 July | Virtual CFO prepares, director approves |
Headquarters | The parent | Monthly close day, quarterly reviews, group audit requests | Virtual CFO with HQ finance |
A parent that closes on working day five cannot wait for filings that settle later in the month. That is why accruals and a fixed cut-off matter.
What Changed in 2026 for Foreign-Owned Subsidiaries?
Several rules shifted between April and October 2026, and each touches a foreign-owned subsidiary’s finance calendar.
Change | Effective | Impact |
Income-tax Act 2025 and Rules 2026 | 1 April 2026 | New “tax year” concept and renamed forms |
Form 48 replaces Form 3CEB | Tax Year 2026-27 | Form 3CEB applies to FY 2025-26 and Form 48 applies from Tax Year 2026-27 |
IT services safe harbour: single 15.5% margin, ₹2,000 crore threshold (EY) | Tax Year 2026-27 | Captive and GCC pricing worth re-testing |
MAT cut to 14% and treated as final tax, for companies not on the concessional 22% regime | 1 April 2026 | No fresh MAT credit |
Export realisation 9 / 12 months | 1 October 2026 | Parent payment terms need review (9 months from shipment for goods, from invoice date for services) |
Four Labour Codes in force | Since November 2025 | Gratuity and provident fund bases to recheck |
Some published commentary still shows the older 15-month window, so verify dates against the primary notification.
When Does a Virtual CFO for Foreign Investor Operations Make Sense?
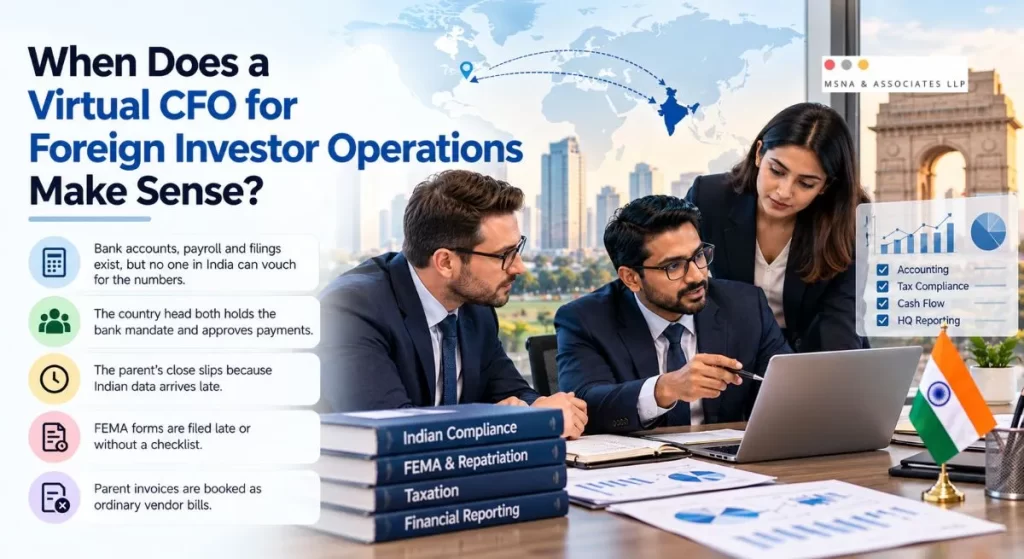
The trigger is rarely size. It is a gap in sign-off. Consider support if:
- bank accounts, payroll and filings exist, but nobody in India can vouch for the numbers
- the country head both holds the bank mandate and approves payments
- the parent’s close slips because Indian data arrives late
- FEMA forms are filed late or without a checklist
- parent invoices are booked as ordinary vendor bills
When it may not fit: a virtual CFO for foreign investors is not always the right model. A handful of transactions is often served by an accountant. A large team may justify a permanent seat; see our interim versus permanent CFO comparison.
Recognise two or more of these signs? A short conversation with a CA team can help you map where your subsidiary’s finance gaps sit.
Who Should Own Your Subsidiary’s Finance? Four Models Compared
Each model suits a different stage of subsidiary growth.
Option | Strong at | Gaps for a foreign-owned subsidiary | Fits when |
Local accountant | Bookkeeping, GST and TDS returns | FEMA view, parent mapping, advisory | Few transactions |
Remote HQ finance team | Group policy, treasury | Indian dates, local sign-off | A short transition |
Full-time India CFO | Daily control | Cost, hiring time, single point of failure | Volumes justify the seat |
Virtual CFO | Books, filings, cash and HQ pack under one lead | Not a statutory officer; does not sign the audit report | Operations exist but no finance owner |
Quarter-One Handover Tracker: What to Hand Over and What to Expect
The first quarter sets the finance habits of the subsidiary, so each phase below lists something you can check.
Phase | What you can check | Needed from HQ |
Week 1 | Handover reviewed; signatory and approval matrix drafted | Incorporation documents, bank mandate, intercompany agreements |
Weeks 2-4 | Chart mapped; compliance register live | Group manual, close calendar |
Month 2 | First close on the agreed date; first HQ pack | Review comments within a set turnaround |
Month 3 | Cash forecast running; intercompany agreement on file | Sign-off on cost policy |
What Are the Five Pressure Points Where Subsidiary Books Drift Off Course?
These five slips recur in new subsidiaries and are inexpensive to prevent early.
- Wiring capital before the bank KYC pack is complete. The 60-day allotment window keeps running.
- Booking parent invoices as vendor bills. Withholding and transfer pricing checks get skipped.
- Recording parent funding as loan balances. External commercial borrowing and equity take different FEMA routes.
- Signing the intercompany agreement after the year ends. Documentation should reflect pricing used during the year.
- Using the HQ ledger as the statutory ledger. The group view should be a mapped layer.
What HQ Finance Teams Typically Ask For
Expectations vary with the parent’s home country and reporting basis.
Parent based in | Typical HQ questions | What the virtual CFO prepares |
United States | US GAAP bridge; control evidence for group audit | GAAP adjustment schedule and documented controls; see US accounting support |
UAE | IFRS alignment; consolidation timing | Mapped trial balance and monthly pack; see UAE accounting and India’s finance talent for UAE businesses |
These are typical patterns, not universal rules.
How Do You Choose CFO Services for Foreign-Owned Companies?
Ask for written answers.
Question | Strong answer |
Who is the named lead? | A named CA with cross-border experience |
What do you file and what do you only advise on? | A responsibility matrix covering MCA, GST, TDS, FEMA and transfer pricing |
Can you work to our close calendar? | A mapped chart and agreed close date |
What will you not sign? | Audit reports, director-signed accounts and bank approvals stay with the right people |
What happens on exit? | Documented handover; data owned by the company |
Compare scope workstream by workstream. A bookkeeping quote and a CFO quote cover different work.
Conclusion On Virtual CFO for Foreign Investor
A virtual CFO for foreign investors turns scattered Indian obligations into one calendar, one set of financial controls and one HQ pack. For a foreign investor in India, that structure often decides whether subsidiary management stays predictable as operations grow.
If you are mapping your subsidiary’s finance function, a conversation with a CA team can help you assess how these rules apply to your structure. You can reach MSNA’s partners or read more in the Virtual CFO knowledge centre.
Managing Finance for Your Indian Subsidiary
Frequently Asked Questions About Virtual CFO for Foreign Investor
What is a virtual CFO for foreign companies?
A part-time senior finance professional who runs accounting, compliance, cash flow and reporting for an Indian entity owned by an overseas parent.
How much do CFO services for foreign companies cost?
Fees follow scope rather than a fixed rate. The main drivers are monthly transaction volume, the number of GST registrations, payroll headcount, the parent’s reporting basis (US GAAP or IFRS), close frequency and the volume of FEMA and transfer pricing work. A scoped quote built workstream by workstream is more reliable than a rate card.
How quickly can a virtual CFO start?
Timing depends on how fast the parent shares documents and bank access. The quarter-one tracker above shows a typical sequence, beginning with a handover review.
Is a virtual CFO useful for an IT or GCC subsidiary?
No. The auditor signs the audit report independently. The virtual CFO prepares books and supports the audit.
Which corporate tax rate applies to an Indian subsidiary?
A domestic company pays 25% or 30% depending on turnover, or opts into the 22% regime (about 25.17% with surcharge and cess), subject to conditions. Confirm your position with a tax adviser
Related
Discover more from MSNA & Associates LLP
Subscribe to get the latest posts sent to your email.