
Financial due diligence is a structured review of a target company’s financial records, earnings quality, cash flows and obligations before a deal closes. Buyers, investors and lenders use it to confirm that reported numbers are reliable and that the asking price matches real value.
This guide covers what financial due diligence involves, why it matters, and how to run it step by step. It also adds a pre-deal screen, a sector lens and Indian tie-out tests, along with 2026 deal data.
In India, a deal can involve the Companies Act, 2013, SEBI takeover regulations, FEMA and competition law, depending on structure, so the numbers must hold up across several regimes. The 2026 market shows why this matters now. Q2 values spiked on large outbound deals and Q3 volumes recovered, so each deal now carries more capital and one missed liability costs more than it did a year ago.
What Is Financial Due Diligence?
Financial due diligence is an independent investigation of a company’s financial health before a merger, acquisition, investment or lending decision.
It tests the validity and sustainability of historical financial performance under new management. The reviewers analyse statements, tax records, debt, cash flows and working capital, and turn the findings into deal terms.
Practitioners often describe three pillars:
- Quality of earnings: how sustainable reported profit really is
- Net debt: every obligation the buyer effectively inherits
- Net working capital: the funds tied up in receivables, payables and inventory to keep daily operations moving
Where Does Financial Due Diligence Part Ways With an Audit?
An audit primarily tests whether statements are fairly presented. Diligence looks ahead at value.
Factor | Statutory Audit | Financial Due Diligence |
Core question | Are the statements fairly presented? | Are earnings real, repeatable and fairly priced? |
Focus | Accounting standards compliance | Value, risk and deal terms |
Output | Audit opinion | Findings with price implications |
Commissioned by | The company | Buyer, investor, lender or seller |
How Does Financial Due Diligence Protect Buyers in Mergers and Acquisitions Deals?
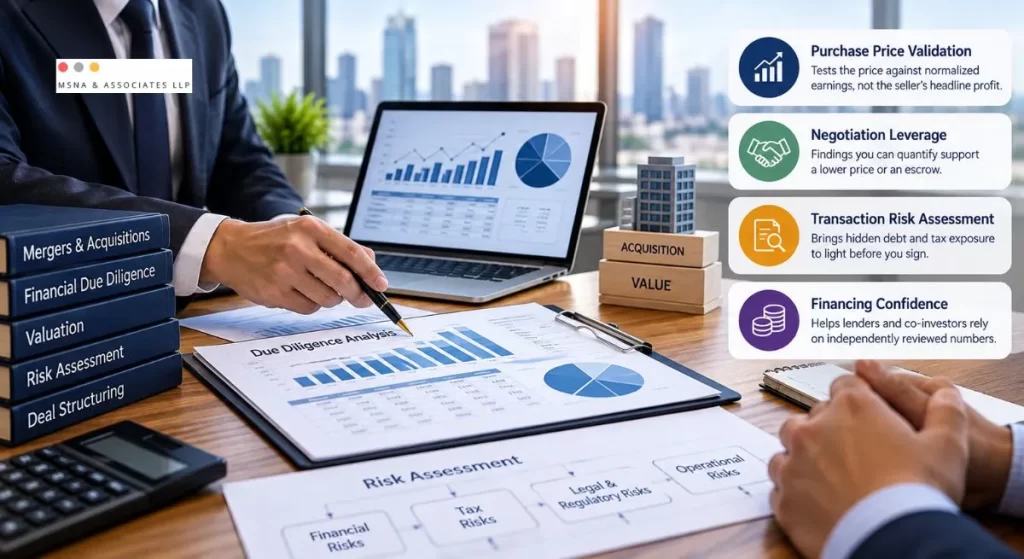
Financial due diligence in mergers and acquisitions protects value at the exact point where mistakes cost the most.
- Purchase price validation tests the price against normalized earnings, not the seller’s headline profit.
- Negotiation leverage comes from findings you can quantify, which back a lower price or an escrow.
- Transaction risk assessment brings hidden debt and tax exposure to light before you sign.
- Financing confidence improves when lenders and co-investors can lean on numbers someone independent has checked.
What Does 2026 Data Say About Financial Due Diligence in Mergers and Acquisitions?
Deal value in India jumped in Q2 2026 on a handful of large outbound transactions, and Q3 then brought deal counts back up.
Metric | Q1 2026 | Q2 2026 | Q3 2026 |
M&A and PE transactions | 686 | 565 | 608 |
Total deal value | $16 billion | $36.3 billion | $23.1 billion |
M&A deals | 271 worth $6.9 billion | 240 worth $27.9 billion | 255 worth $13.2 billion |
Outbound share of M&A value | 56% | 84% | not reported |
Source: Grant Thornton Bharat, via IANS (Q1) and its Q2 and Q3 2026 Dealtrackers. Q3 totals are the sum of the reported M&A and PE figures
BCG analysis of the first seven months of 2026 adds that volumes are down nearly 20% while value slipped only 2%. Fewer deals carrying similar capital means each valuation error costs more.
Why Do Deals Fail Without Proper Diligence?
Several advisors point to the same weak spot, which is earnings quality.
Source | Finding |
Bain’s 2020 report, citing earlier surveys of senior executives | Almost 60% of executives blamed disappointing deals on diligence that missed critical issues |
QoE and other diligence findings together account for nearly half of failed US mid-market transactions | |
Adjusted earnings before interest, tax, depreciation and amortisation (EBITDA) can differ from reported EBITDA by 30 to 50% or more in owner-operated businesses |
Diligence findings, including earnings quality, are the largest single group of reasons deals fail.
Who Needs Financial Due Diligence and When?
Financial due diligence services matter to anyone committing capital or control based on another party’s numbers.
Audience | Typical trigger | Main concern |
Business owners | Selling, merging or raising capital | Presenting defensible numbers |
CFOs and finance managers | Acquisition or carve-out | Reporting and integration load |
PE and VC firms | Platform or growth investment | Earnings quality and valuation |
Investors and lenders | Debt or equity ticket | Cash coverage and covenants |
M&A advisors | Mandate execution | Findings that survive negotiation |
Buy-side reviews confirm value and find risk. Sell-side reviews remove surprises early. Startups raising capital face a version of the same test, and a virtual CFO for Series A funding often builds investor-ready numbers months ahead.
What Should Be on Your Financial Due Diligence Checklist?
Eight areas cover most of what a buyer needs to see.
Area | What to review | Red flag |
Financial statement review | Three to five years of statements, trial balances, policies | Policy changes that lift profit |
Revenue verification | Contracts, invoices, customer ageing | Heavy concentration in a few customers |
Debt and liabilities assessment | Loans, guarantees, leases, contingent claims | Commitments outside the balance sheet |
Cash flow analysis | Operating cash against EBITDA, capex | Profit without matching cash |
Working capital assessment | Receivables, payables, inventory trends | Payables stretched before a sale |
Tax and statutory dues | Income tax, GST, TDS, PF and ESI | Open assessments and mismatches |
Related parties | Transactions, balances, pricing | Non-arm’s-length dealings |
Controls and reporting | Month-end close, systems, approvals | Slow close and manual workarounds |
Weak controls often show up in the last row, and an internal control over financial reporting (ICFR) audit checklist is a handy way to test them.
Financial Due Diligence Process: How Does a Review Run From Start to Finish?
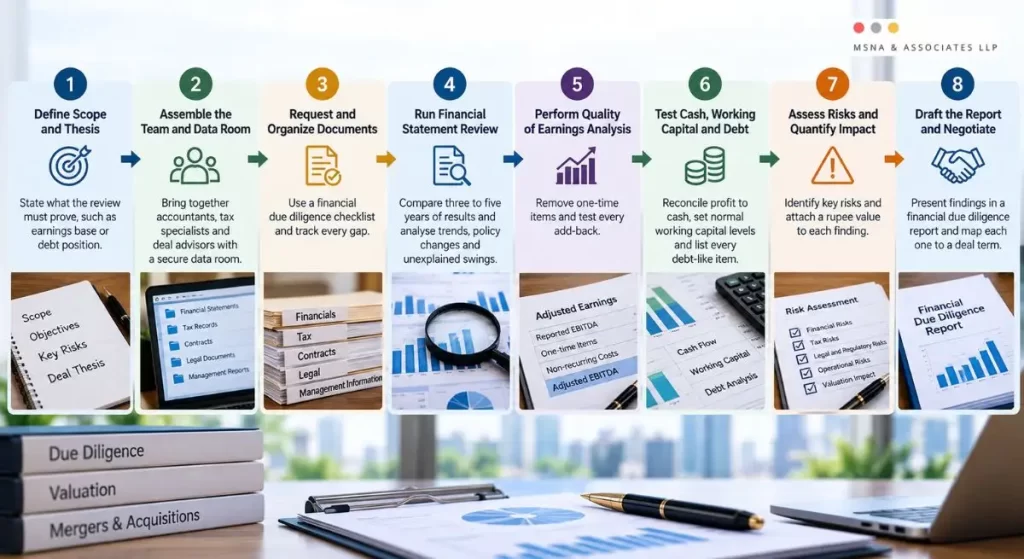
The financial due diligence process runs through eight stages, and each one feeds the next.
Step 1: Define Scope and Thesis
State what the review must prove, such as the earnings base or the debt position. Tight boundaries prevent wasted effort, a principle covered in our guide to the scope of an internal audit. The same discipline serves due diligence in business acquisition.
Step 2: Assemble the Team and Data Room
Accountants, tax specialists and deal advisors should share one secure data room.
Step 3: Request and Organize Documents
Turn the financial due diligence checklist above into a numbered request list and track every gap.
Step 4: Run Financial Statement Review
Compare three to five years of results. This stage hunts for trends, policy changes and unexplained swings in historical performance
Step 5: Perform Quality of Earnings Analysis
Strip out one-time items and test every add-back, as the next section shows.
Step 6: Test Cash, Working Capital and Debt
Reconcile profit to cash, set a normal working capital level and list every debt-like item.
Step 7: Assess Risks and Quantify Impact
Attach a rupee value to each finding, because a finding only helps when it feeds the price.
Step 8: Draft the Report and Negotiate
Present findings in a financial due diligence report and map each one to a deal term.
How Does Quality of Earnings Analysis Work in Financial Due Diligence?
Quality of earnings analysis converts headline profit into sustainable profit, which is the number a buyer should actually pay for.
EBITDA Analysis and Normalization
Earnings Before Interest, Taxes, Depreciation, and Amortization (EBITDA) analysis starts with the seller’s figure and adjusts for items that will not recur or were mis-timed. The table is illustrative and reflects no client.
Line item | INR crore |
Reported EBITDA | 50.0 |
Add back one-time legal settlement | +2.0 |
Remove non-recurring export incentive | -3.5 |
Normalize promoter salary to market | -1.5 |
Reverse revenue booked before delivery | -4.0 |
Adjusted EBITDA | 43.0 |
At an illustrative 10x multiple, the 7 crore gap moves the price by 70 crore. Share-based payment charges such as ESOP costs call for a separate judgement. They are non-cash, yet a buyer may treat them as a real cost of keeping key staff, so agree the treatment before the add-backs are totalled.
Revenue Verification
- Trace sample invoices to contracts and bank receipts
- Test cut-off around period ends
- Review credit notes issued after year end
- Confirm the revenue recognition policy: Ind AS 115 for entities that follow Ind AS, AS 9 for those that do not
Working Capital Assessment
- Compare monthly averages, not year-end snapshots
- Watch for receivables built up or payables delayed before signing
- Agree a target level that goes into the purchase agreement
Cash Flow Analysis
- Check how much EBITDA converts to operating cash
- Separate maintenance capex from growth spending, where a virtual CFO for capex planning can bring structure
- Flag businesses that profit on paper but borrow to operate
Net Debt and Debt-Like Items
Item | INR crore |
Bank borrowings | 30.0 |
Accrued interest | 0.8 |
Lease liabilities | 3.2 |
Unpaid statutory dues | 1.5 |
Gratuity and bonus shortfall | 2.0 |
Less: cash and bank balances | -7.5 |
Net debt | 30.0 |
At the illustrative 10x multiple, adjusted EBITDA of 43.0 crore implies an enterprise value of 430 crore. Deducting net debt of 30.0 crore leaves an equity price of 400 crore. Debt-like items found in diligence are normally deducted from enterprise value to reach the equity price, subject to what the parties agree.
Which Financial Due Diligence Findings Change the Deal?
A finding matters only when it changes price, structure or the decision to proceed.
Finding | Typical deal response |
Long list of recurring add-backs | Price on adjusted, not reported, EBITDA |
Revenue recognized early | Price reduction and tighter definitions |
Hidden or contingent liabilities | Specific indemnity or escrow |
Working capital drain before closing | Adjust the working capital target |
Related-party leakage | Pre-closing clean-up |
Unreliable records | Extend the timeline or exit |
We group these responses into four levers: reprice, restructure, protect or walk away. Every finding should land in one of them.
How Can You Screen a Target Before a Full Review?
A five-question screen, run before signing a letter of intent, saves cost on weak targets and sharpens the first bid.
- Does profit convert to cash? Compare three years of EBITDA with operating cash flow.
- Do revenue figures agree across sources? Match books, GST returns and bank credits.
- How concentrated is revenue? Check the share held by the top five customers.
- How large are the add-backs? Compare total add-backs with EBITDA. The engagement team sets the threshold for further review
- How fast do the books close? A slow month-end points to weak records.
Failing two or more is a reason for a lower opening bid or a closer look, not automatic rejection.
A professional review can show how these five answers read against a specific target’s records. MSNA’s team is available to discuss how the screen applies to your transaction
What Changes in Financial Due Diligence for an Indian Acquisition?
Due diligence for an acquisition in India adds several India-Specific layers.
- Confirm which accounting standards the target follows and align policies before comparing
- Review promoter and group-entity transactions closely
- Check open tax disputes and other contingent claims
- Confirm whether approvals apply under the SEBI (SAST) Regulations, 2011, the Competition Act, 2002 or the FEMA NDI Rules, depending on structure
Then run four tie-outs between records that should agree:
Record A | Record B | What a gap may signal |
Revenue in books | Sales in GSTR-1 and GSTR-3B | Unrecorded or mis-timed sales |
Purchases and input credit in books | Eligible credit in GSTR-2B | Ineligible credits or doubtful vendors |
Receipts in books | Bank credits, and customer TDS in Form 26AS and AIS | Fictitious revenue, round-tripping or unreported income |
Payroll cost | PF and ESI returns, and salary TDS returns (Form 24Q) | Unpaid statutory dues |
A gap is a question, not a verdict. Each one deserves an explanation from management.
MSNA supports India-side diligence for US and UAE acquirers and does not act on the buyer’s home-country filings. Global teams also compare buying an Indian business with building one, and the cost to set up a GCC in India gives a useful build-side benchmark.
How Does Financial Due Diligence Differ by Sector?
The same framework applies everywhere, but the pressure points shift by industry.
Sector | Focus area | Question to ask |
IT and SaaS | Deferred revenue, churn, contract terms | Is recurring revenue contracted or merely repeated? |
Manufacturing | Inventory valuation, capex, capacity use | Is maintenance capex being deferred? |
Export businesses | Forex exposure, incentives, receivable ageing | How much profit depends on incentives or currency moves? |
Retail and consumer | Inventory, discounts, lease obligations | How much value sits in leases and returns? |
What Happens After Financial Due Diligence?
Findings only pay off when they reach the agreement and the first 100 days.
Common deal tools include:
- Escrow or holdback: part of the price is retained against future claims
- Specific indemnity: the seller covers a named exposure
- Earn-out: part of the price depends on future performance
- Working capital target: a fixed benchmark adjusted at closing
After closing, hand the findings to integration owners. Fix the month-end close, reporting and controls early, because gaps there often prove costly when ignored.
What Should a Financial Due Diligence Report Include?
A strong report is light on narrative and heavy on decisions.
- Executive summary of key findings
- Normalized EBITDA bridge
- Net debt and debt-like items
- Working capital target analysis
- Risk register with quantified exposure
- Recommended protections in the agreement
Expert Insight: How Do Experienced Advisors View Financial Due Diligence?
“Many buyers treat diligence as a hunt for errors. The better question is what each finding is worth in rupees and where it belongs in the agreement. A finding that becomes a price change, an escrow or an indemnity has done its job.
” Naveen S N, Co-Founder, MSNA & Associates LLP
Clean books are also a negotiating asset. Well-documented add-backs and a timely month-end close make a seller’s numbers easier for a buyer to verify.
How Can MSNA Help With Financial Due Diligence?
If you are evaluating a target in India, MSNA’s team can discuss the scope of your financial due diligence services needs, from earnings review to debt checks. The discussion can also cover how the pre-deal screen and the four tie-out tests in this guide apply to your target.
Consulting a professional early can help you assess how these checks apply to your transaction before you submit a bid. You can start a conversation through our financial due diligence services page.
Understand the Financial Risks Before Your Next Deal
FAQs About Financial Due Diligence
What are the three pillars of financial due diligence?
Quality of earnings, net debt and net working capital. Together they set the price a buyer should rationally pay.
How long does financial due diligence take?
The financial due diligence process often runs three to six weeks for mid-market deals. Data readiness drives the range.
What affects the scope of a financial due diligence engagement?
Deal structure, target size, number of entities, period under review, and data readiness. The buyer’s main concern, such as earnings quality, debt, or tax exposure, also shapes the focus
Who conducts financial due diligence?
M&A financial due diligence is usually led by chartered accountants and transaction advisors, working with legal and tax specialists.
Can financial due diligence detect fraud?
It can surface warning signs, but it is not designed to guarantee fraud detection.
What documents are needed?
Multi-year financial statements, tax filings, debt agreements, customer and vendor contracts and monthly management accounts.
Related
Discover more from MSNA & Associates LLP
Subscribe to get the latest posts sent to your email.